

Should I File an Insurance Claim After a Car Accident if I Am Not at Fault in Florida?
Being involved in a car accident can be overwhelming, especially if the crash wasn’t your fault. You may be wondering whether it’s worth filing an insurance claim or if doing so could even hurt your premiums. Due to Florida’s unique no-fault insurance laws, the answer isn’t always straightforward.
At RTRLAW, we help accident victims across Florida understand their rights and maximize their compensation even in cases when they weren’t responsible for the crash. We can explain what you need to know if you’re not at fault and wondering whether to file an insurance claim.
What is Florida’s “No-Fault” Insurance System?
Florida is one of the few states that operates under a “no-fault” insurance system. This means that after a car accident, your own insurance company, regardless of who caused the accident, is responsible for paying your medical expenses and lost wages through Personal Injury Protection (PIP) coverage.
Every Florida driver is required to carry a minimum of $10,000 in PIP. This covers:
- 80% of the necessary medical expenses
- 60% of lost wages
- $5,000 in death benefits (if applicable)
However, PIP does not cover non-economic damages like pain and suffering, nor does it cover vehicle repairs or damage to property. That’s why even if you’re not at fault, you may need to pursue additional claims outside of your PIP benefits.
WBJ Adventures
They are amazing very grateful for whar they did for my father, they are very attentive on everything, Emily Chica was so nice , she always keeps us informed on calls and emails, very grateful thank you 🙏 if we need again for sure you guys will be the ones we will look for 🙏🙏
When Should You File a Claim with the Other Driver’s Insurance?
While you’re required to use your PIP coverage first, you may have the right to file a claim against the at-fault party’s insurance in certain circumstances.
This is especially important when:
- Your injuries are severe or permanent
- Medical bills exceed $10,000
- You experience long-term disability
- Your vehicle is damaged or totaled
In these cases, a third-party liability claim can help you recover:
- Medical expenses beyond PIP limits
- Property damage (vehicle repairs or replacement)
- Pain and suffering
- Future medical expenses or lost earning capacity
In such situations, filing a third-party claim allows you to seek compensation for damages not covered by PIP, such as pain and suffering, future medical care, and long-term wage loss.
Should I File a Claim Even for Minor Accidents?
Yes, you should still file an insurance claim, even if the accident seems minor. Some injuries take days or weeks to appear, and skipping the claims process can limit your legal rights later.
Also, Florida law requires that you seek medical treatment within 14 days of the accident in order to access your PIP benefits. Failing to report the accident or delaying medical care could jeopardize your ability to recover compensation.
Even when the damage seems small, reporting the accident and filing a claim protects your interests and builds a paper trail.
What Happens if the Other Driver is Uninsured or Underinsured?
Unfortunately, not all drivers in Florida carry adequate insurance. If the driver who caused your accident is uninsured or underinsured, you may need to rely on your own Uninsured/Underinsured Motorist (UM/UIM) coverage.
UM/UIM coverage is optional in Florida, but it’s strongly recommended. It can help cover your:
- Medical bills
- Lost wages
- Pain and suffering
If you carry this coverage and the at-fault driver lacks enough insurance, you can file a claim under your own policy. It’s a smart safety net in a state with one of the highest rates of uninsured drivers in the nation.
Will Filing a Claim Affect My Insurance Rates if I’m Not at Fault?
Many drivers fear that filing a claim, even when they’re not at fault, will raise their insurance premiums. In most cases, however, insurance companies are not supposed to raise your rates for a not-at-fault accident.
That said, every insurer has different underwriting policies, and multiple claims, regardless of fault, could still impact your premiums. It’s important to review your policy and speak with an experienced attorney if you’re concerned about rate increases or bad-faith practices by your insurer.
Why is it Still Important to Notify Your Insurer After an Accident?
Even if you don’t plan to file a claim, you should still notify your insurer about the accident. Most policies require that you report any incidents involving your vehicle, even those caused by someone else.
Failing to notify your insurer could result in denial of future coverage or problems down the line. Reporting the accident simply protects your rights and gives you more options if medical issues or repair costs arise later.
How to File an Insurance Claim When You Are Not at Fault in Florida: Step by Step
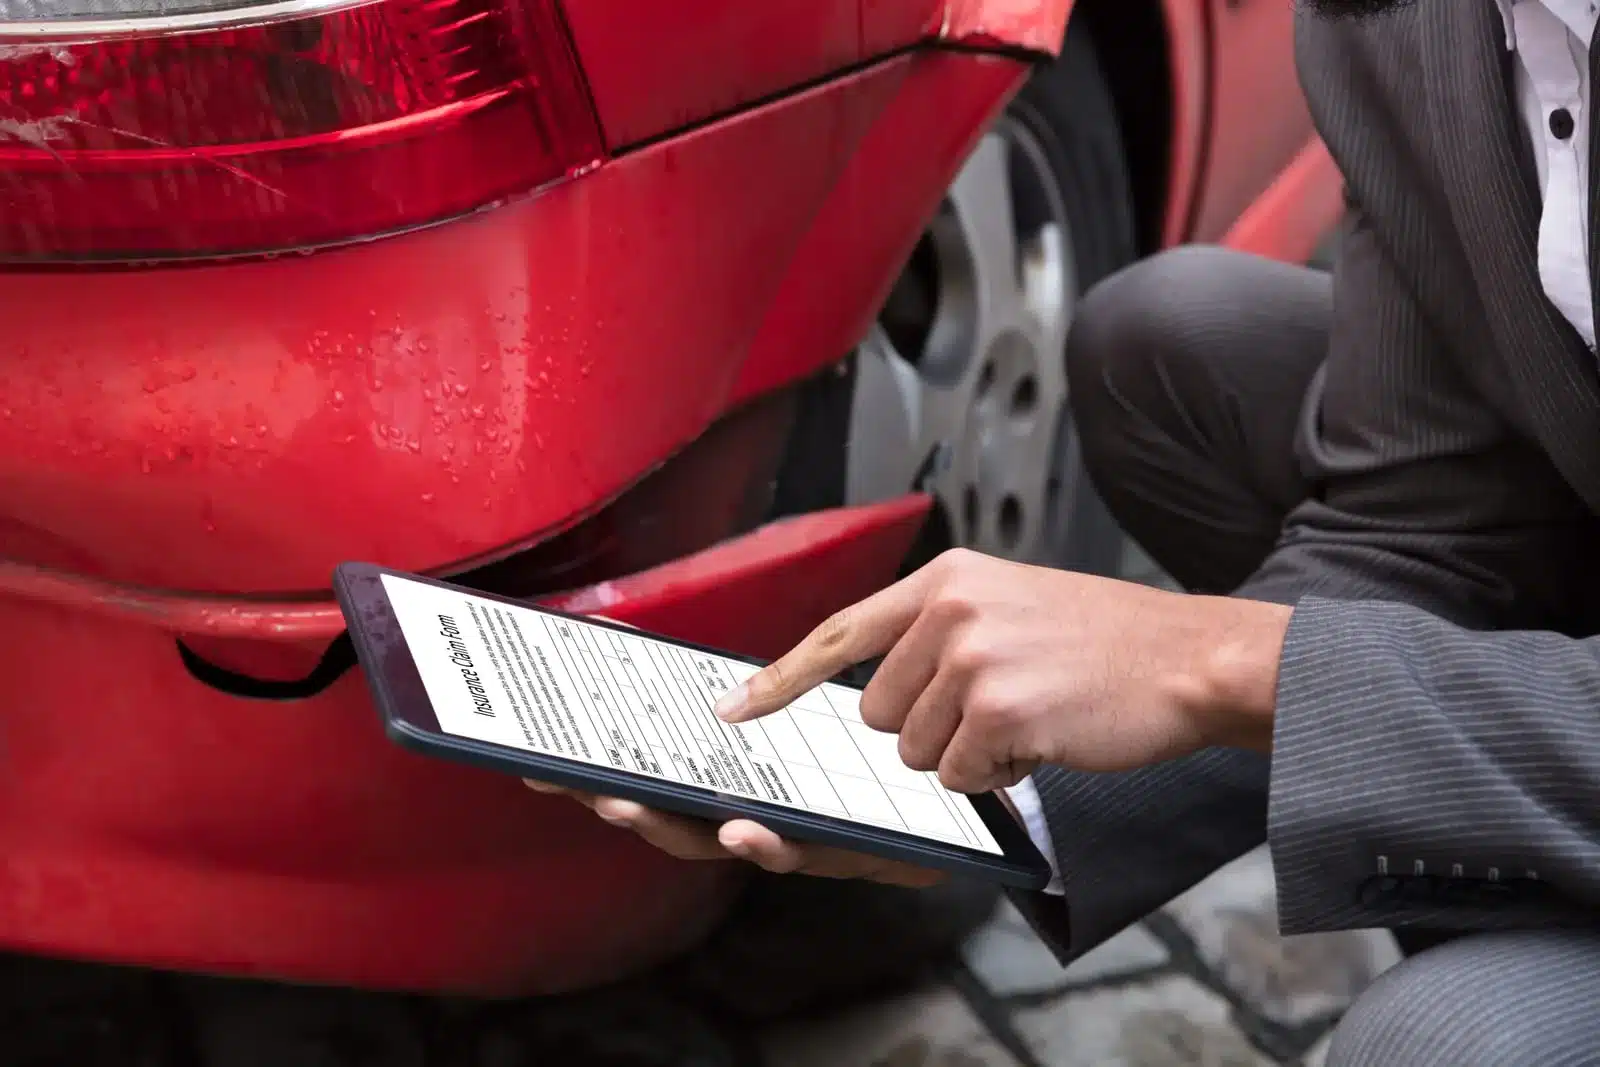
Being innocent of causing the crash does not eliminate the insurance claims process in Florida. Because Florida uses a no-fault Personal Injury Protection system for certain accident-related medical and disability benefits, you may need to deal with your own insurance company as well as the at-fault driver’s insurer.
Here is how the process generally works:
1. Report the Accident and Document What Happened
Contact law enforcement when appropriate and obtain the crash report information if an officer investigates the collision. Take photographs or video of the vehicles, damage, roadway, traffic controls, injuries, debris, skid marks, and anything else that may help show how the accident occurred.
2. Notify Your Own Insurance Company
Tell your auto insurer about the accident promptly, even when another driver caused it. Provide the basic facts necessary to report the collision, but avoid guessing about injuries, speeds, distances, or other details you do not know.
3. Get Medical Care Within 14 Days
Florida’s PIP law generally requires initial medical services and care within 14 days of the motor vehicle accident for PIP medical benefits to apply. Do not delay necessary treatment simply because your symptoms initially seem manageable.
4. Open Your PIP Claim
Your own PIP coverage is generally the first source of certain medical and disability benefits after a Florida motor vehicle accident, regardless of who caused the crash. Keep your claim number and maintain copies of medical records, bills, correspondence, and other documents you receive from the insurer.
5. Address Your Vehicle Damage
Property damage is handled differently from PIP medical benefits. Depending on the circumstances and the coverage available, you may pursue the at-fault driver’s property damage liability insurance or use applicable coverage under your own policy.
Keep repair estimates, towing bills, rental vehicle expenses, photographs, receipts, and documentation showing the pre-accident condition and value of the vehicle.
6. Document Every Loss Connected to the Accident
Insurance claims are supported by evidence rather than estimates made from memory months later. Maintain records of missed work, wage loss, medical expenses, prescriptions, transportation expenses, property damage, and other financial consequences of the crash.
You should also keep track of how the injuries affect ordinary activities, work responsibilities, sleep, mobility, and your ability to do things you could do before the collision.
7. Be Careful With Statements and Early Settlement Offers
The other driver’s insurance company may contact you for a statement or ask you to sign medical authorizations, releases, or settlement documents. Be cautious about making definitive statements concerning your injuries before you know their full extent or accepting a settlement that releases claims for future losses.
Once a claim is fully released, you generally cannot return later simply because an injury turned out to be more serious than expected.
8. Determine Whether You Have an Additional Claim Against the At-Fault Driver
PIP does not necessarily compensate an injured person for every loss caused by a crash. Depending on the nature of your injuries, available insurance, and other circumstances, you may also have a claim against the driver or another party responsible for the collision.
The fact that you were not at fault does not mean the insurance process will automatically resolve itself in your favor. Following the correct steps, meeting Florida’s deadlines, and preserving evidence from the beginning can make it much easier to establish what happened and document the full extent of your losses.
Work with RTRLAW & Get the Compensation You Deserve
Just because you weren’t at fault doesn’t mean you should avoid filing a claim. In fact, filing both a PIP claim and possibly a third-party liability claim can help you cover expenses, recover losses, and protect your long-term health and finances.
Florida’s no-fault system doesn’t mean fault doesn’t matter; it just changes how and when you pursue compensation. At RTRLAW, our experienced attorneys can guide you through every step after an accident, help you gather evidence, and handle communication and issues with the insurance companies on your behalf.
If you’ve been injured in an auto accident in Florida, don’t wait. Call us at 1-833-HIRE-RTR or reach out for a free consultation today. We’re here to help protect your rights so you can move forward with strength.